Exactly how I run an optimized life without optimizing every minute
The practical operating layer behind Mr ROI: assigned accounts, a weekly review, repeatable meals, concentrated luxuries, a home built as infrastructure, and deliberate areas left alone.
In brief
What I learned
Give each account and card a clear job, automate routine transfers, pay cards in full and review the system weekly.
Build the week around a few anchors: focused work, repeatable food, coordinated home tasks, training, and a short reset. Keep fallback versions for compressed days.
Concentrate spending where repeated use and personal interest justify it. My car, theater and audio, home gym, office, and home earn more than equal slices because they shape daily life.
The point is fewer active decisions
I like working out the best way to do things. I don't like having to make the same decision over and over. That's why I automate boring obligations, set defaults for meals and training, and spend attention on the parts of life that actually deserve it. A good system should give me time back, not create another dashboard I have to babysit.
This is the implementation layer behind the broader Mr ROI operating system. It describes my defaults without publishing balances, income, private account details, or a fantasy minute-by-minute routine.
The reusable decision method behind this personal setup is The Mr ROI Operating System.
Every financial account gets one job
The operating account handles normal cash flow. A bills lane isolates predictable obligations. A reserve protects short-term flexibility. Sinking categories prepare for irregular costs such as home, vehicle, travel, or equipment. Long-term investing is not treated as spare checking money.
The labels matter less than separation. If one balance has to answer whether the mortgage is covered, whether a repair is affordable, and whether a vacation is funded, it creates avoidable ambiguity.
- Lane
- Operating
- Job
- Normal income and day-to-day spending
- Review trigger
- Weekly category or cash-flow surprise
- Lane
- Bills
- Job
- Known recurring obligations
- Review trigger
- Price increase or failed automatic payment
- Lane
- Reserve
- Job
- Unexpected cost and optionality
- Review trigger
- Use, target change, or coverage risk
- Lane
- Sinking categories
- Job
- Expected irregular purchases
- Review trigger
- Timeline or quote changes
- Lane
- Long term
- Job
- Future compounding
- Review trigger
- Scheduled allocation review, not daily headlines
My systems exist to make the important decisions less frequent, not to make every minute feel managed.
Credit cards are routing tools, not borrowed lifestyle
Each card needs a reason to exist: a useful category, purchase protection, travel benefit, or credit-history role. Automatic payment protects the deadline, but I still review statements for wrong amounts, duplicate charges, renewed subscriptions, and offers that create value without changing the purchase.
Paying the statement balance in full matters more than extracting another reward point. A carried balance can erase the return from an elaborate rewards system very quickly.
My weekdays run on anchors
The day begins with the work that requires the clearest thinking. Food is built from repeatable options so hunger does not launch a fresh research project. The afternoon includes the coordination and communication that accumulates around work and the house. Training has a known slot on the days it occurs. The evening ends with a short reset, not a second shift of optimization.
A compressed day keeps the anchors and removes optional detail. That may mean a simpler meal, the fallback workout, one critical house task, and no recreational research. The goal is continuity rather than perfect completion.
The weekly review is the control panel
Once a week I look for drift, not perfection. The questions are written so they produce an action. A number without a decision is just dashboard decoration.
- Area
- Money
- Question
- What changed or renewed?
- Possible action
- Cancel, dispute, reprice, or update the plan
- Area
- Work
- Question
- What creates the most leverage next week?
- Possible action
- Block the analysis, memo, meeting, or skill work
- Area
- Training
- Question
- Did performance and recovery trend together?
- Possible action
- Progress, hold, or use the fallback week
- Area
- Food and home
- Question
- What friction repeated?
- Possible action
- Prep one staple or fix one root cause
- Area
- People
- Question
- Who needs attention, clarity, or appreciation?
- Possible action
- Schedule the conversation instead of mentally carrying it
The house is infrastructure
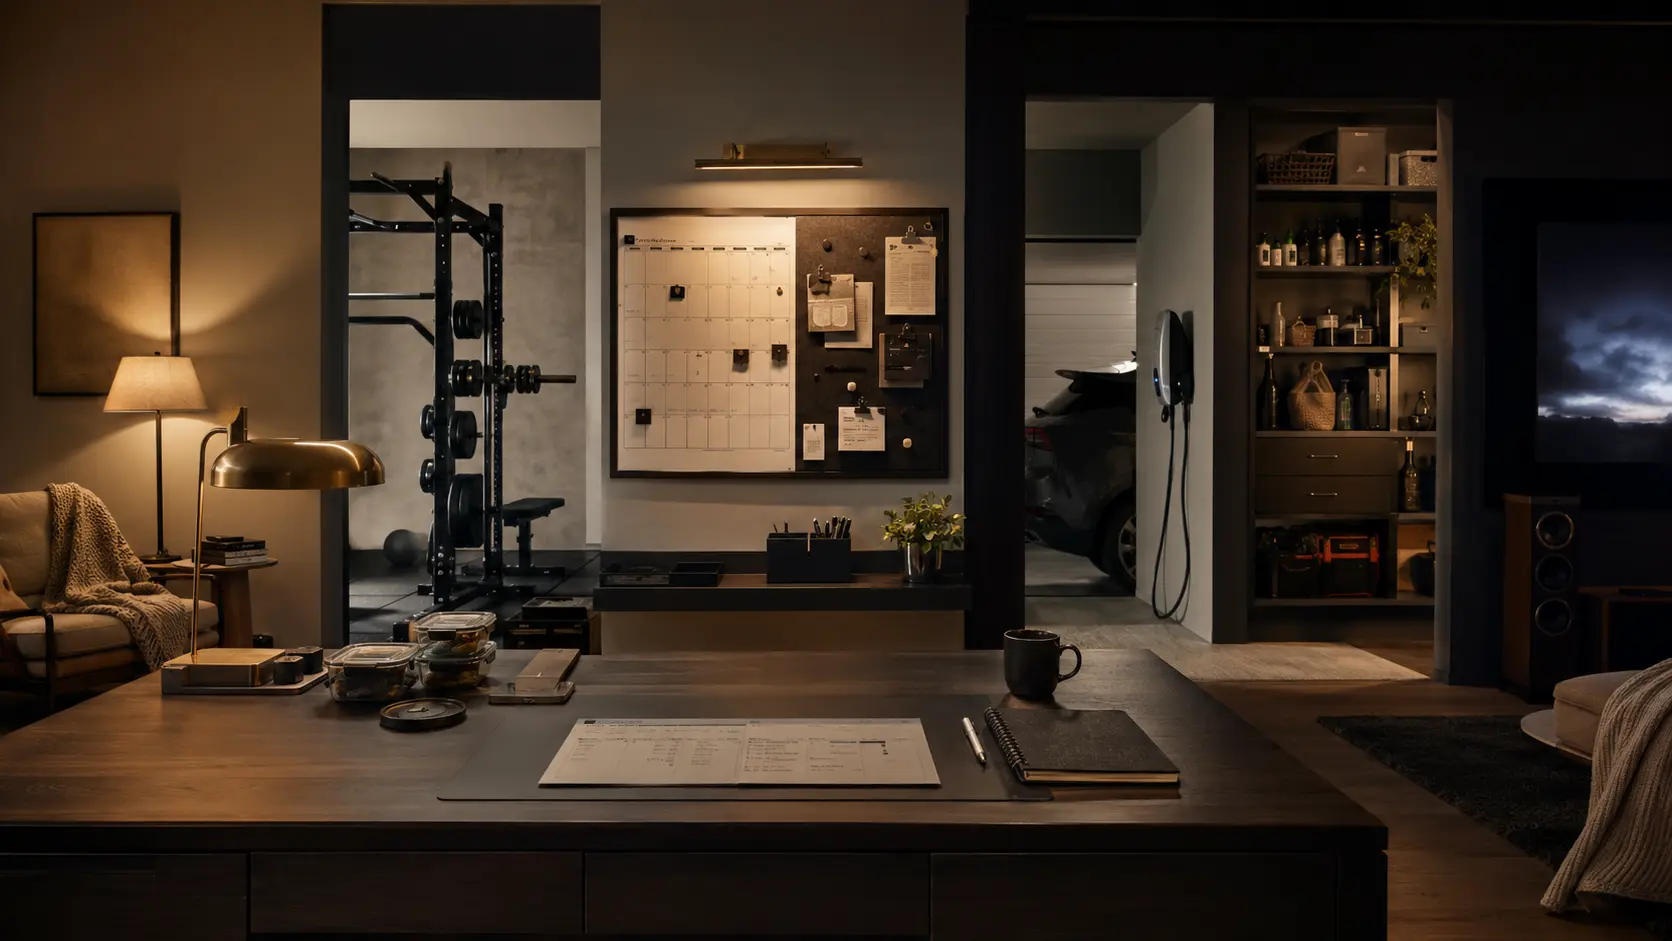
Living at home until 21 gave me time to prepare for ownership rather than treating rent as a mandatory rite of passage. The house Rebecca and I bought now supports the life we actually live: a serious home gym, theater and audio, office, useful kitchen, storage, and charging.
Those rooms save travel, support hobbies, and make high-use time better. They also create maintenance. Every upgrade needs a storage, cleaning, repair, power, network, and eventual replacement plan. The ROI comes from repeated use, not from calling every expensive room an investment.
Technology must remove recurring work
Rocket Money helps surface subscriptions and recurring charges. Price alerts wait on purchases. Wearables show trends. A password manager and multifactor authentication reduce the chance that convenience creates a security debt.
I keep a tool when it shortens a repeated task, improves a material decision, or protects an important system. I remove it when the subscription becomes the thing I am managing.
I deliberately overspend in a few categories
Equal spending is not balanced spending. My car, home theater and audio, fitness equipment, office, and the house itself receive more attention because I use them constantly and care about them. The rest of life is allowed to be ordinary.
The constraint is that premium purchases need a job. They should improve repeated use, remove friction, protect health or time, or create an experience I knowingly value. I do not need to claim that every luxury pays me back financially.
The review cadence prevents permanent tinkering
Weekly reviews catch drift. Monthly reviews cover subscriptions, cash flow, training blocks, and upcoming maintenance. Quarterly reviews question the tools and projects that have expanded. A yearly review asks whether the house, work, spending, and routines still support the life we are building.
Between reviews, the default wins. That rule is how optimization creates freedom instead of consuming it.
Sources
Disclosure
Some links may earn Mr ROI a commission at no added cost to you. That does not change the recommendation. This is general information, not personal financial or medical advice. Read the full disclosure.